The 'Fake Hybrids' (PHEV) Trap in Belgium: Rules, Calculation, and Tax Penalties
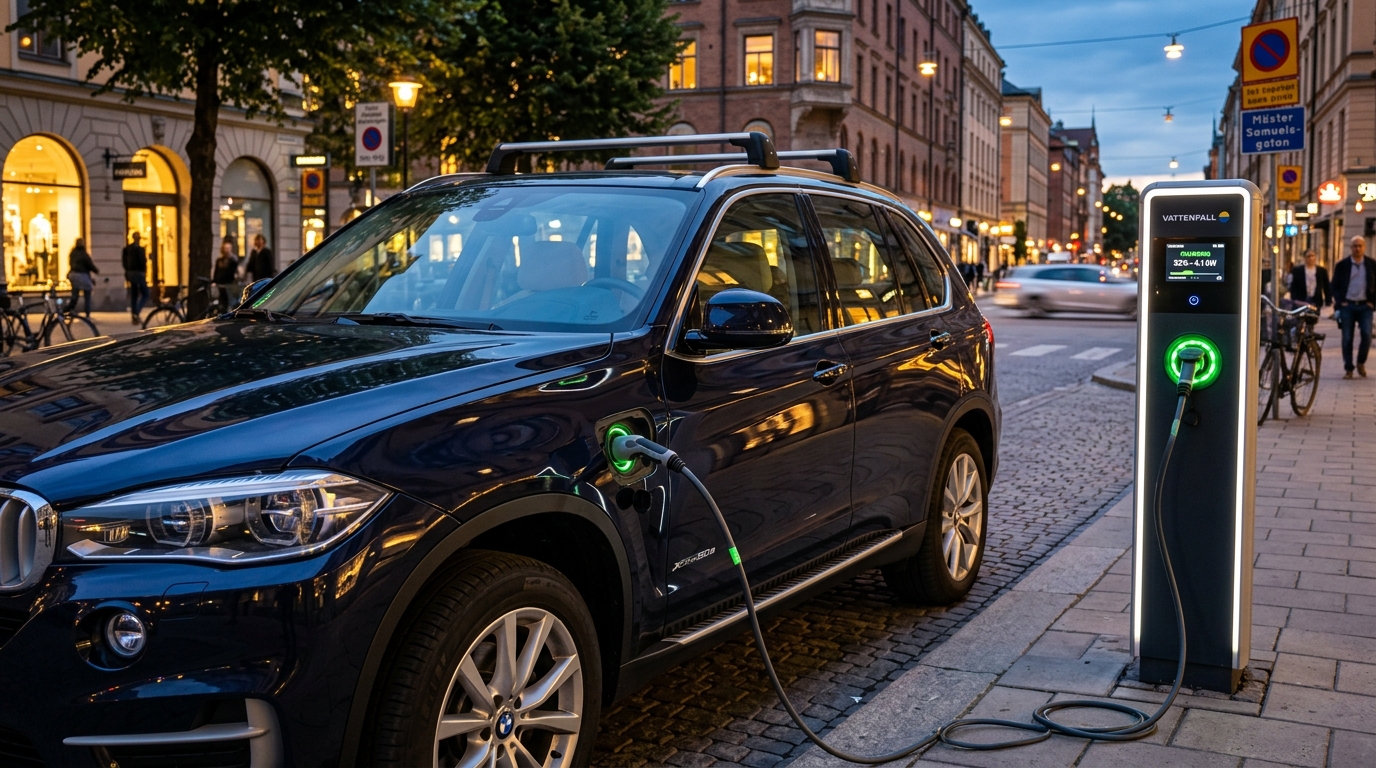
In the pre-owned vehicle market, company executives and private motorists are frequently enticed by luxury plug-in hybrid (PHEV) SUVs advertising low fuel consumption of 2 liters/100 km and emissions ratings between 35 and 48 g CO₂/km. However, when tax season arrives, the shock is severe: the vehicle is legally reclassified by Belgian tax authorities as a 'fake hybrid' (valse hybride). As a result, personal Benefit-in-Kind (BIK) surges to the maximum legal cap, corporate deductibility plummets, and regional registration taxes skyrocket.
1. Legal Framework: Article 65 of the Belgian Income Tax Code (CIR 92)
During the mid-2010s, several carmakers fitted heavy luxury combustion vehicles with undersized batteries (6 to 9 kWh) specifically to exploit European laboratory test cycles. On testing rollers, these vehicles drove initial kilometers in electric mode, securing artificial emissions scores while consuming over 10 liters/100 km in real-world driving.
To close this tax loophole, the Belgian Federal Parliament enacted the Program Law of December 25, 2017, codified in Article 65 of CIR 92 and clarified by administrative Circular 2021/C/8.
2. The Two Cumulative Criteria for a 'Genuine Hybrid'
To maintain preferential fiscal treatment and utilize its official low-CO₂ rating, a PHEV must satisfy both criteria simultaneously:
Certified mixed WLTP CO₂ emissions must not exceed 50 grams per kilometer. Any rating of 51 g/km or above triggers instant disqualification.
Gross battery storage capacity in kilowatt-hours divided by vehicle curb weight (per 100 kg increment) must equal at least 0.500.
3. Statutory Penalty: Discarding the Green Rating
If a vehicle fails either criterion, the tax authorities completely disregard the official CO₂ value. In its place, the tax office substitutes the CO₂ emission rating of the equivalent purely combustion-powered vehicle in the manufacturer's catalogue.
If no direct combustion equivalent exists, the law mandates an automatic 2.5x multiplier on the vehicle's official CO₂ rating!
4. Severe Financial Repercussions
- Surge in Driver BIK (ATN): The statutory taxable rate jumps to the legal ceiling of 18% of catalog value. For an €80,000 SUV, monthly taxable BIK increases from ~€190 to over €1,000 per month!
- Collapse of Corporate Tax Deductions: Corporate vehicle expense deductions drop to 40%–50% (and phased out completely under current corporate tax schedules).
- Flemish BIV Shock: The Flemish Tax Administration (Vlabel) calculates registration tax using the substituted combustion CO₂, levying bills in excess of €2,500 to €4,500 instead of minimal green vehicle fees.
5. Common Pitfall Models in the Used Car Market
| Model | Battery | Curb Weight | Ratio | Status |
|---|---|---|---|---|
| BMW X5 xDrive40e (F15) | 9.0 kWh | 2,305 kg | 0.390 kWh / 100 kg | FAKE HYBRID |
| Porsche Cayenne S E-Hybrid (Gen 1) | 10.8 kWh | 2,425 kg | 0.445 kWh / 100 kg | FAKE HYBRID |
| Mercedes C 350e (W205 pre-facelift) | 6.2 kWh | 1,780 kg | 0.348 kWh / 100 kg | FAKE HYBRID |
| Volvo XC90 T8 (pre-late 2021) | 11.6 kWh | 2,390 kg | 0.485 kWh / 100 kg | FAKE HYBRID |
| BMW X5 xDrive45e (G05) | 24.0 kWh | 2,510 kg | 0.956 kWh / 100 kg | GENUINE HYBRID |
Estimate your taxes for this vehicle
Use our free calculator to estimate registration tax (BIV/TMC), annual road tax, and corporate BIK.